 by
The Chicago multifamily outlook changed again in September when the Federal Reserve raised the federal funds target range by 25 basis points to 3.75%–4.00%. For apartment owners, however, the practical conclusion is not that cap rates automatically move by the same amount. Property pricing is determined by a wider set of variables: actual debt costs, lender proceeds, sustainable NOI, buyer return requirements, competing supply and the depth of qualified demand.
At the same time, national multifamily supply pressure is beginning to ease. Yardi Matrix reported that advertised rents increased for a sixth consecutive month in August while starts and deliveries have declined materially from the 2023–2024 cycle highs. That combination makes the current market more nuanced than a simple “rates up, values down” headline.
For Chicago-area owners deciding whether to sell, refinance or continue holding, five signals deserve particular attention.
Recent Chicago market reporting reinforces the need to separate national headlines from local property performance. Northmarq’s Q2 2026 Chicago multifamily review found rent growth across both urban and suburban areas, with some of the strongest performance concentrated near the urban core. That local resilience does not eliminate financing or expense pressure, but it does make property-specific underwriting more important than a one-line market call.
1. Policy Rates Are Not Cap Rates
The Federal Reserve’s September action matters because it influences the broader cost of capital. But the federal funds rate is not a multifamily mortgage rate, and neither is it a cap rate.
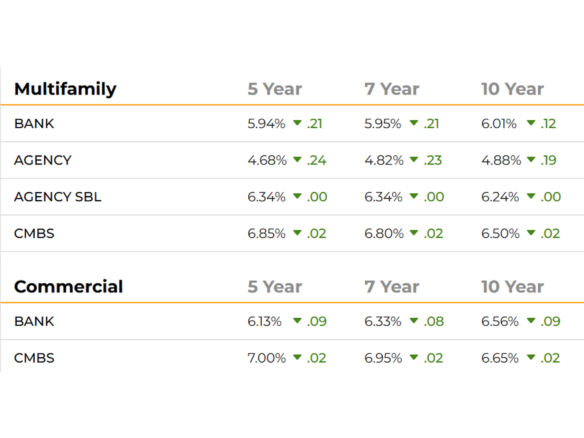
Apartment debt is ultimately priced through a combination of benchmark rates, lender spreads, loan structure, leverage, property quality, borrower strength and market conditions. A buyer’s required return also reflects the property’s expected NOI growth and risk profile. Those inputs do not move in lockstep.
This distinction matters when an owner receives a quick valuation based primarily on a single cap-rate assumption. A credible multifamily Broker Opinion of Value should reconcile comparable sales, current operations and the debt proceeds available to likely buyers.
2. New Supply Is Slowing—and That Matters for Existing Properties
One of the more constructive multifamily signals is the changing supply pipeline. Yardi Matrix reported in September that U.S. advertised rents rose again in August as the supply wave receded. The firm also noted that starts and deliveries have fallen substantially from recent cycle highs.
For existing Chicago-area apartment properties, lower future construction can improve the competitive environment over time. Fewer new units competing for renters can support occupancy and rent growth, although the impact varies substantially by submarket and property class.
Owners should therefore avoid treating national construction statistics as a direct forecast for an individual building. The relevant question is what is being delivered—and what is no longer being started—within the property’s actual competitive set.
3. Rent Growth Helps, but Sustainable NOI Drives Value
Rent growth receives most of the attention. Buyers, lenders and appraisers ultimately underwrite net operating income.
A property can post higher rents while producing limited value growth if taxes, insurance, utilities, repairs or other operating costs absorb the gain. Conversely, a well-operated property with documented collections, defensible expense normalization and identifiable operational upside can create a stronger underwriting story.
Before marketing an apartment building, owners should reconcile the rent roll to actual collections, review the trailing 12-month operating statement, separate recurring expenses from unusual items and identify which adjustments a buyer and lender are likely to accept. Our multifamily sale-preparation guidance addresses this process in greater detail.
The objective is not to manufacture a higher NOI. It is to present the property’s economics accurately and prevent avoidable underwriting discounts.
4. Lending Is Available, but Financeability Still Separates Buyers
Capital remains available for multifamily acquisitions, but disciplined underwriting has not disappeared. Buyers must still satisfy lender requirements for debt-service coverage, leverage, debt yield, property condition and borrower liquidity.
That creates an important seller-side distinction between a buyer who can submit a price and a buyer who can finance and close at that price.
During a competitive sale process, I evaluate more than the headline offer. Earnest money, due-diligence structure, financing contingencies, lender credibility, appraisal exposure, buyer track record and closing timing all affect execution certainty. My recent guide to multifamily offer terms explains why the highest nominal price is not always the strongest economic outcome.
5. Sell, Refinance or Hold? Test the Alternatives Against Each Other
For many long-term apartment owners, the hardest question is not whether the property has value. It is whether selling creates a better outcome than continuing to own it.
Self-managed properties can produce attractive current cash flow. A refinance may provide liquidity without triggering a taxable sale. A disposition, however, can reduce management exposure, diversify concentrated wealth, support retirement or succession planning, or allow capital to move through a 1031 exchange into another apartment property, a DST or an appropriate net-leased investment.
Those alternatives should be evaluated before an owner commits to a transaction. Closing timing, tax planning and replacement-property strategy can influence which offer structure is actually most useful.
A broker cannot replace the owner’s attorney, tax adviser, lender or wealth adviser. A strong investment-sales process should coordinate with those professionals so the real-estate transaction supports the owner’s broader objectives rather than operating in isolation.
What the September Fed Hike Means for Chicago Apartment Owners
The September rate increase is relevant, but it is only one input. Slower construction, improving national rent trends, property-specific NOI and the availability of acquisition financing are moving simultaneously.
That is why the current Chicago multifamily outlook should be evaluated property by property. An owner considering a sale does not need a generic market prediction. The useful analysis is what qualified buyers can finance today, what return they require for the specific asset and how much competitive demand exists at the resulting price.
Through eXp Commercial’s National Multifamily Division, I combine professional underwriting, comparable-sale analysis, lender-aware pricing, curated buyer outreach and broad market exposure to help Chicago-area multifamily owners test those questions before committing to a sale strategy.
Considering a sale, refinance or hold decision? Request a confidential Broker Opinion of Value to understand current pricing, buyer demand and execution considerations for your property. Request a confidential property valuation or schedule a call.