 by
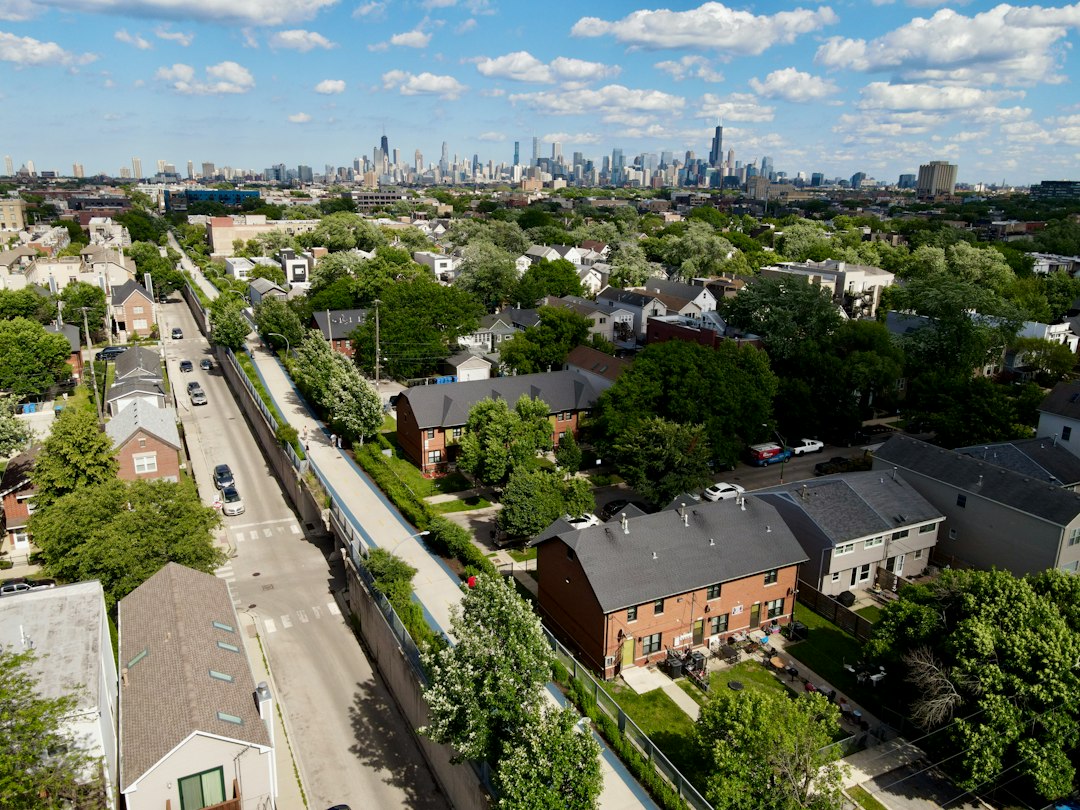
Chicago-area apartment owners can see stable occupancy and healthy metro rent headlines while individual units compete in a much narrower market. For owners evaluating renewal rents, renovations, refinancing or a sale, the critical question is not simply whether Chicago apartment rents are rising. It is which units a prospective tenant can realistically choose instead—and what that competition means for sustainable net operating income (NOI).
Fresh local evidence reinforces the need for granular underwriting. RentCafe’s October 8, 2026 rental-competitiveness analysis ranked Chicago first among major U.S. rental markets, with approximately 17 prospective renters per available apartment and a 27-day average vacancy period. In its separate Suburban Chicago category, the analysis recorded approximately 13 prospective renters per vacancy, a 70.8% lease-renewal rate and 37 average vacant days. These figures reflect a dataset of conventional multifamily properties of 50 or more units; they are not measurements of every small apartment building or a guarantee of pricing power in a particular neighborhood. Yardi Matrix’s September 2026 Chicago report similarly described comparatively strong rent performance and occupancy. Metro demand signals support buyer interest but cannot replace property-level effective rent and NOI verification.
The actual competing rent set matters more than the metro average
A 1960s twelve-unit building in an established Cook County suburb does not compete equally with every downtown high-rise. Its relevant alternatives may include nearby vintage walk-ups, partially renovated Class B buildings, smaller condominium rentals, townhomes, newer apartments offering concessions and, in some neighborhoods, income-restricted communities. Competing stock depends on location, unit size, parking, condition, laundry, utilities, lease terms and renter eligibility.
The proper rent comparison measures achievable effective rent, not only advertised asking rent. A unit offered at $1,800 with one free month on a twelve-month lease produces $1,650 per month of first-year effective rent before other costs. Concessions, tenant-paid utilities, included parking, pet policies and move-in costs must be normalized to avoid overpricing the subject.
Do affordable and market-rate apartments compete for the same renters?
Sometimes—but not automatically. Affordable housing, naturally occurring affordable housing (NOAH) and conventional market-rate apartments are different categories. Regulated units may have household income qualification, rent limitations and different availability. NOAH generally refers to unsubsidized apartments whose rents are relatively attainable because of age, size, location or condition. Conventional Class B/C assets often face the closest competition when two properties offer similar cost and utility to the same renter household.
An industry discussion at Yardi Matrix’s November 2026 affordable housing outlook emphasized comparing properties at the submarket and unit-type level. For an owner, that means a practical check of real alternatives for a one-bedroom apartment in Aurora, a two-bedroom in Joliet or a three-bedroom in a Cook County neighborhood—rather than assuming the same demand dynamics apply across the entire metropolitan area.
Turn occupancy and advertised rent into defensible NOI
Underwriting should connect the rent roll to actual cash flow. Begin with contractual rents and payment history, then account for vacancy, concessions, delinquency, bad debt, miscellaneous income and recoverable versus owner-paid utilities. Subtract normalized taxes, insurance, management, repairs, turnover, utilities and other recurring operating expenses. Separate capital improvements from operating expenses and disclose any seller-specific adjustments.
Consider an illustrative twelve-unit property where comparable evidence supports an additional $50 per unit per month. At full occupancy, that is $7,200 of annual gross potential rent. At 95% economic collection and assuming no added operating expenses, approximately $6,840 flows through to NOI. At a purely illustrative 6.50% capitalization rate, that represents roughly $105,000 of capitalized value. Neither the rent increase nor the cap rate is a Chicago market quotation. If turnover costs, vacancies or taxes absorb the incremental income, the value effect is smaller.
This is why a valuation based on a rent-only upside schedule can overstate buyer proceeds. A qualified buyer will ask what part of that upside is already achieved, how quickly leases expire, how much capital is needed to capture it and whether lenders will recognize the stabilized income.
Four operating questions Chicago-area apartment owners should answer now
- Which five to ten rentals are true substitutes? Compare unit type, concessions, condition, utilities, parking, transit access and lease timing—not merely ZIP code or an online median.
- What is the actual renewal versus turnover economics? Test modest renewal increases against vacancy days, make-ready work, leasing costs and payment performance.
- Are expenses eroding rent growth? Review property taxes, insurance renewals, repairs and management costs before projecting net income.
- How much of the potential NOI can a buyer finance? Model in-place income separately from achievable stabilized income, with current lender debt-service coverage and reserve requirements.
The investment-sales implication
An owner deciding to sell, hold or refinance needs two numbers: a properly normalized in-place NOI supported by operating records, and a market-stabilized NOI supported by defensible rent comparables and a realistic execution plan. A strong leasing market is valuable, but unsupported rent premiums are not automatically reflected dollar-for-dollar in a buyer’s offer.
That distinction is important for both smaller two- to four-unit properties and institutional-scale multifamily portfolios across the greater Chicago area, including Cook, DuPage, Kane, Will, Lake, McHenry and Kendall counties. A credible disposition strategy can position proven operations and attainable upside differently rather than presenting one optimistic number.
For a broader capital-markets perspective, see our 2027 multifamily outlook for Chicago apartment owners. To discuss property-specific rent positioning, valuation or an investment sale, schedule a confidential consultation with Randolph Taylor, MBA, CCIM, MiCP, Vice President, Multifamily Investment Sales Broker, eXp Commercial National Multifamily Division.
Market data referenced above are attributed to Yardi Matrix as of the cited reporting period. Illustrative calculations are not an appraisal, a current cap-rate quotation or a prediction of investment returns. Property-level underwriting requires independent verification.